
Ray, 76, pulled a folder of slip invoices across the table and let me do the math on a boat he had already sold. The purchase price was the cheap part, and getting that wrong costs years you cannot buy back.
Eight weeks, three Phoenix-area retirement communities, 50 retirees ages 62 to 84, a notebook and one question: where did the money go that you would never spend again? I bought none of these things myself, and I made follow-up calls to read the actual numbers off their statements.
Not one of them regretted a dollar of the fun. What they regretted was the bill that kept arriving after they stopped using the thing. Ten purchases here, buy price and keep cost side by side, and the check that would have caught each one before the money left.
By the end you should have your own list sorted, plus one job for this week.
Quick Tips Before You Start
Pull 12 months of statements
Print or download every bank and card statement from the last year and highlight the repeating charges.
Add the keep cost
For any big purchase, write the annual cost—insurance, maintenance, fees—next to the purchase price.
Set a waiting rule
On any non-essential over $500, wait 30 days before signing. Most regrets never survive the wait.
Get the fee table
Before signing any financial product, ask for the fee disclosure and the surrender schedule in writing.
Cancel one recurring charge
Find the one membership or subscription you can't defend and cancel it this week.
Bought in the first year
The first year of retirement is when the big purchases happen. You've got a lump sum, a pension, or just the feeling that you've earned something. That feeling is expensive.
Three of the first items on this list were bought within twelve months of a last day at work. The pattern was consistent: the purchase price was known, the keep cost was not.
1. The boat lost $17,000 for nine afternoons

I sat with a man named Ray who can answer that with his own money. He was 76, in his first year out of work, and he wrote the check for $38,000. Nineteen months later he sold it for $21,000. The resale slip is the number I keep coming back to: $17,000 gone before a single slip fee ever hit his account.
The slip, the insurance and the service ran about $6,100 a year, and across those 19 months he took the boat out nine times. Nine. The keep cost was running every month whether he untied the lines or not – the marina billed him in January the same as July, and the boat sat there.
Here is where I tell you to bring in someone whose numbers are your numbers. Before you sign, get written charter quotes for two or three days out on the same water, add them up against a full year of ownership, and let a fee-only planner or the marina's own service manager run your total. The charter quote is the check. It catches this one before the cash leaves, and it costs you nothing but an afternoon of phone calls to find out.
💡 Tip: Price two or three charters against a full year of ownership before you buy. The charter quote is the check.
| Item | What they paid | What it costs to keep | What they'd do instead |
|---|---|---|---|
| Boat | $38,000 | $6,100/yr slip, insurance, service | Price two or three charters against a year of ownership |
| Lake condo | $212,000 | $9,400/yr taxes, HOA, utilities, upkeep | Compare six weekends of renting to the annual carrying cost |
| Retirement truck | $52,000 ($31,000 financed) | $840/yr extra insurance plus payment | Keep the paid-off sedan unless the truck is weekly equipment |
| Kitchen remodel | $6,800 | Same three feet of counter | Remodel for Tuesday cooking, not twice-a-year holidays |
| Timeshare | Initial price plus $2,400/yr maintenance | $189 booking fee per stay | Book the same week annually or check state consumer agency before paying exit fees |
| Storage unit | $310/mo | About $22,000 since 2019 | Inventory the unit, compare fees to replacement value |
| Auto-renewing memberships | Monthly fees | Twelve months paid for three used | Pull 12 months of statements, cancel the undefended one |
| Annuity | Initial premium | Annual fee and seven-year surrender period | Ask for the fee table and surrender schedule before signing |
| Extended warranty | $1,900 | Zero claims | Check manufacturer warranty first; fund a repair line instead |
| Advisor fee | Percentage of assets | Ongoing fee for a once-a-year call | Ask what the fee is in dollars and what it buys |
2. The lake condo bills $9,400 for six weekends
The belief I heard most often was that a second home pays for itself eventually, that the equity is the point and the weekend visits are just a bonus. Helen, 69, put $212,000 into a lake condo 240 miles from her house because she believed that, and she still does. But a boat is sold and the loss shows up in one clean number, while a house sits on the books looking like wealth and pays out its carrying cost a little at a time, all year, whether anyone is there or not.
Her taxes, HOA dues, utilities and upkeep run about $9,400 a year.
That is the number she quoted me off the statement without hesitating, and the number she had never once compared with the number of times she drove up. Six weekends, that year and most years. Six weekends starts with four hours of highway each way on a Friday afternoon, which one of those weekends she described as the closest thing to a second job she has ever had.
call the local weekly rental rate on that lake, multiply by six, then look at $9,400 a year and decide which number you would rather pay. In most of the cases I ran, the rentals won by a margin wide enough that she did not need the exact figure to see it, only the order of magnitude in front of her.
The version that works is a different person with a different calendar. Someone who takes the whole month of July, or whose family shows up there all summer, gets real use out of $9,400 and can defend it out loud. That is the rule, and it is not a close call for anybody in between.
The purchases we regret are almost never the expensive ones. They're the ones that keep billing after the pleasure stopped.
— What 50 retirees kept saying in different words
3. The retirement truck added $840 a year in insurance

Price the monthly difference before you trade the keys. A car you own outright and one you finance to celebrate retirement look almost identical in the driveway – the same paint, the same smell inside. The number that separates them arrives every month, and it keeps arriving long after the occasion is forgotten. Where the condo at least sits on an asset that has a market price, a car bought in place of a paid-off one is the same drain with nothing to sell at the end, because you turned a thing you owned into a thing you owe.
Gus, 74, did exactly that. On his last day of work he traded a sedan that had no payment on it for a $52,000 truck and financed $31,000 of it. He didn't buy a toy. He traded owned for owed, and that is the part he kept returning to when we talked.
The insurance went up $840 a year on top of the payment. That is not the biggest line in his budget, but it climbs onto a bill that was zero before. Three years in, the truck has 11,000 miles on the odometer. A working truck earns its miles; his mostly sat in the driveway looking handsome.
Here is the honest trade-off, because there is a real one. A vehicle that celebrates a milestone gives you something no spreadsheet can measure – the first morning you don't clock in, and the keys are in your hand. I understand that feeling, and I am not going to pretend it is worthless.
But you should know what it costs you to buy it. Run the payment, the insurance bump and the annual registration against what the old car cost – often close to nothing beyond gas and maintenance. That difference is the real price of the celebration, and it comes out of money you will want in fifteen years, when the truck is old and the payment is a distant memory.
So do the math on the whole package before you sign. Add the monthly payment to the insurance increase, multiply by twelve, and ask yourself if that yearly number is worth the feeling you are buying. For a lot of retirees, once the number is written down, the answer changes on its own.
This truck is genuinely fine for someone who tows a trailer or hauls for a real weekly hobby – a boat, a camper, lumber for the shop. That person uses it as equipment, and the miles on the odometer show it. The truck that sits at 11,000 miles after three years is the one I would put back on the lot and think about for a week.
💡 PRO TIP
The two-column test
Before any purchase over $500, write what it costs to buy in one column and what it costs to keep—per year, per outing, per weekend—in the other. If the keep column is longer than the use column, you have your answer.
Bills that keep arriving
The first group was money already spent and visibly gone. This group is worse: money leaving every month for things no longer used.
The keep cost doesn't care whether you use the thing. The bill arrives on schedule.
4. The remodel built for holidays hosted two of them

I sat in Tom and Paula's kitchen for an hour before I understood the thing I was actually looking at. The counters were the same three feet of laminate they had always been. The room around them was new.
They spent $6,800 rebuilding a kitchen for family holidays that came twice in four years. Paula was the one who did the cooking both times, in the same three feet, for a crowd that showed up and left before the second Sunday. So what did the $6,800 buy? A room that looks different on a Tuesday while the Tuesday stays the same.
Here is the automation I took away from their house. Before you sign a remodel contract, put three months of ordinary weeknight meals on paper and nothing else – who cooks, how often, where they stand. If the plan you drew on that page doesn't match the drawings from the contractor, the drawings wait. The holidays get a folding table and a spare oven rack for $0.
Tom said it plain: they built for the guest list and should have built for the calendar.
If you already host monthly and the list proves it, remodel away – that's a house earning its keep. If the family comes twice a year, the fix isn't the counters. It's a card table and a decision to let the room be what it is.
5. The timeshare bill arrives whether they go or not

What I heard most from the people who owned timeshares wasn't anger at the price. It was a quieter thing – the feeling of getting billed for a version of their life that had stopped happening.
Dana, 71, has a Sedona unit. Maintenance runs $2,400 a year, plus $189 to book a stay. She has used it twice in four years. The fee doesn't care that she didn't go. It fills the gap between the habit she imagined and the weekends she actually had. When she tried to get out, a resale outfit wanted money upfront before anything changed hands. My advice from eight weeks of calls: never pay a stranger to take a timeshare. Call the resort and your state consumer agency first.
For the person who books the same week every year and shows up, the fee is the price of a habit. For everyone else, it's the price of a hope.
💡 Tip: Never pay a stranger an upfront fee to take a timeshare before checking with the resort and a state consumer agency.
Timeshare: keep or exit
Worth keeping if
- You book the same week every year and show up
- The maintenance fee is the price of a habit, not a hope
- You've used it at least three of the last four years
- You can afford the fee without touching other savings
Time to exit if
- You've used it fewer than once a year
- The maintenance fee has risen faster than your budget
- You're paying booking fees on top of maintenance
- You're keeping it because selling feels like admitting a mistake
6. The storage unit has cost $22,000 for old furniture
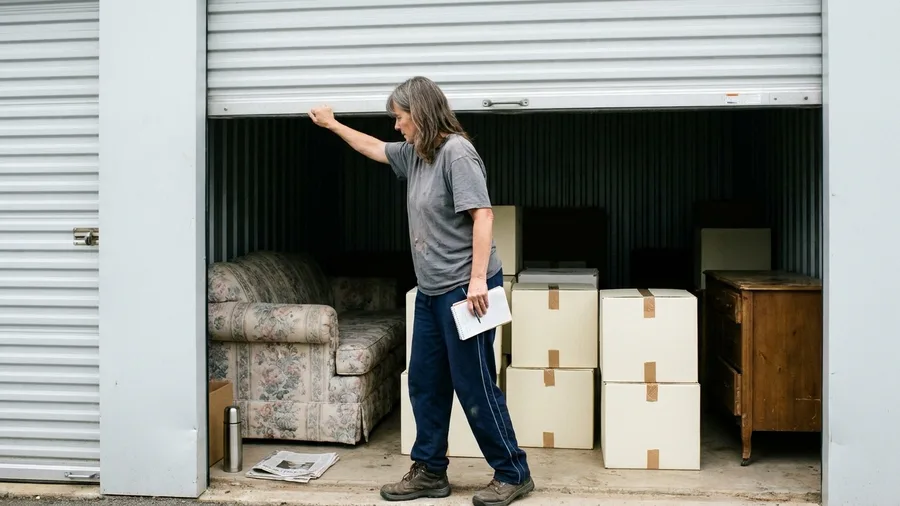
$310 a month is what Carol, 68, has been paying for a storage unit since 2019. Add it up. That's about $22,000.
The inventory I'd ask her to run – and the one I'd ask you to run – is small and brutal. Walk in with a pad. Write down every piece that would actually hurt to lose. Then price what it would cost to replace only the useful ones. When the months of fees climb past the replacement value, the unit isn't storing your furniture. It's storing the fee.
Set a review date on the calendar. Every twelve months, look at three numbers: the monthly rent, the current replacement value of everything you'd genuinely rebuy, and the last time you visited. If two of those three fail, that's the month to empty it.
One exception, and it's real: a documented move with an end date. Write the month on the calendar before the first payment leaves your account. If you can't name the month, you don't need the unit – the stuff just needed a place to sit while you decided.
One week to sort the recurring charges
7. Auto-renewing memberships outlive the hobby

Pull twelve months of bank and card statements and read the repeating lines, not the big ones.
That is the whole move, and it takes one afternoon. A storage unit is a single line large enough that you notice it. The quiet money is different: a gym, a golf club, a streaming bundle, a museum membership, a wine club, each billed to a card on a schedule nobody re-reads. The trap is the monthly-versus-annual gap, paying for twelve months of something you used three, because the charge was small enough to ignore. Twelve months of statements is how you find them all at once instead of one greeting at a time.
One rule before you cancel anything: keep the membership you actually used forty times last year. That one is a bargain and it stays.
Paperwork, fees and add-ons
This group is different. These were not purchases you could see. They were terms set by documents signed without reading.
The fix is not willpower. It's a reading habit.
8. The annuity's exit terms were on page nine

Signing something at a bank branch feels final in a way a membership page never does, because nobody wants to admit at the counter that they don't understand the papers in front of them. That discomfort is normal, and it is not a reason to sign anyway.
Denise, 66, bought an annuity there in 2019 and six years later still could not tell me what she was paying for it. The contract carried a seven-year surrender period, which is the window during which pulling your money out costs you a penalty, and an annual fee that was printed on a page she had turned past without reading. The paperwork was complete and legal. It was also unread.
The mistake is not stupidity, it is sequence. People read the headline rate on page one and sign, when the pages that decide what the thing actually costs are the ones at the back nobody hands you first.
What she asks for now fits on three lines: the fee table, the surrender schedule, and a straight answer to what it pays and when. Before signing, the same three questions go to the plan's own fee disclosure and to FINRA's fund analyzer, and no rate gets quoted anywhere in this piece because the number belongs to the document, not to me.
An annuity can be the right tool for someone who wants a guaranteed income floor and has read every page, surrender schedule included. The point is not to avoid it. The point is to sign the pages you've actually read.
9. The $1,900 warranty covered a fridge that never broke

$1,900. That is what Tom and Paula, 72 and 70, paid for a five-year extended warranty on a refrigerator, added at the register on top of the appliance price. In five years the fridge never needed a repair, so the $1,900 bought nothing but the feeling of being covered.
That is the whole pitch, and it is worth seeing clearly: you are paying once, upfront, on a bet that something breaks. The bet is priced by the only party at the counter who has the repair data, and it is priced to win.
The same offer arrives at the register for everything from a microwave to a washing machine. It is a routine, not a warning, and that routine is why saying no feels rude rather than sensible.
So start small and start here: before you add anything on top, read what the manufacturer's warranty already covers. Most appliances come with a year or more of parts and labor protection, and the extended plan usually begins where that coverage ends, which means you may be buying time you already own.
Now the permission. You do not have to feel certain about every appliance in your house to skip these. You only have to ask one question at the counter: what would a repair actually cost me, and can I cover it from savings?
For a $1,900 warranty, the better home for that money is a repair line inside the emergency fund. An account with even $500 set aside for the fridge, the furnace or the water heater pays out on whichever one actually fails, not just the one you happened to insure. That is the small start that keeps working after the policy would have expired.
There is one exception worth naming: a single big-ticket item whose repair would wreck the month. In that case the warranty is doing real work. For most appliances, the repair line does it better, and the money stays yours when nothing breaks.
So the next time the register asks, you have a move: read the manufacturer's terms, put $50 a month into the repair line, and walk out with the appliance and the $1,900 still in your account. Small, automatic, and pointed at every appliance you own.
💡 Tip: Check your credit card's extended warranty benefit before buying a store warranty.
Extended warranty vs. repair fund — the math
💵 Warranty cost
$1,900 for five years
🔧 Claims made
Zero
🏦 Repair fund alternative
$1,900 earning interest
📅 Coverage window
Five years
🧾 What manufacturer warranty covers
Read the fine print first
The rule
Self-insure anything you could replace without wrecking your month; insure only what you couldn't.
10. The advisor fee was the biggest bill of all

Pull the last statement and divide the fee by the balance. A 1% charge on $500,000 is $5,000 annually, and it compounds against you every year it stays. That clock is why this question waits for nobody.
One woman I interviewed, 66 and retired, had been paying a percentage of her portfolio for a single yearly phone call and a statement she handed me and couldn't explain. We found the fee printed in the account paperwork, not on the summary page. She moved to a flat-fee planner, then sat across from the next one and asked two things: what is this in dollars, and what do I get? Before you sign, look the planner up in the SEC's and your state's investment-adviser database and read their Form ADV – it lists how they're paid.
Ongoing paid advice earns its keep for a pension election, a business sale, a blended family's estate. If your money is simple, a fee-only fiduciary for a few hours may cover it. Run the number first; the clock won't wait.
Frequently Asked Questions
Is it too late to change my spending habits after retirement?
No. The retirees I spoke with were between 62 and 84, and most had already made changes. The first step is pulling twelve months of statements and looking at the repeating charges. That alone often frees up more than a new budget would.
How much should I keep in an emergency fund in retirement?
A common target is one to three years of essential expenses in cash or a high-yield savings account, because you're no longer earning a paycheck to refill it. Start with one month of bare expenses—rent, food, utilities, insurance—and build from there.
Should I pay off debt or invest first?
If the debt carries a high interest rate, like a credit card at 20% or more, paying it off is usually the better return. For lower-rate debt like a mortgage, it depends on your tax situation and comfort with risk. Run the numbers against your own budget before deciding.
Is a timeshare ever worth keeping?
It can be, if you book the same week every year and actually go. If you've used it fewer than once a year and the maintenance fee keeps rising, it's worth looking into exit options. Never pay an upfront fee to a company that promises to take it off your hands without checking with the resort and a state consumer agency first.
How do I find a financial adviser who won't overcharge me?
Ask for the fee in dollars, not percentages, and ask what it buys. Check the adviser's Form ADV and their record through the SEC or your state's investment-adviser lookup. A flat-fee planner for a one-time plan is often enough for people without complex situations.
What's the first thing I should cancel?
The subscription or membership you haven't used in three months and can't defend. Pull twelve months of statements, highlight every repeating charge, and cancel the one that makes you wince. Then set a calendar reminder to review the list again in six months.
Your Own Never-Again List Starts With Recurring Charges
Sort your own list by recurring charges first, because those are the ones still running, then the one-time purchases, where the fix is a waiting rule: write the price down and let a statement cycle pass before you sign.
This week, pull twelve months of statements, put every repeating charge on one page, and cancel the one you cannot defend out loud. Then go back to Ray's folder of slip invoices, which is where I started. The retirees who came out fine were not the ones who spent least. They were the ones who knew what each thing cost them per year.
Some of these ten are genuinely fine, and I would say so to anyone: the boat for the person on the water weekly, the condo for the month-at-a-time stayer, the truck for the one hauling for a real hobby, the timeshare for the owner who books the same week and shows up, storage with an end date, one membership used forty times, an annuity read to the last page, a warranty on the one repair that would wreck the month, and advice for a plan complicated enough to need it.
Do the twelve-month check this week
Pull your statements, highlight every repeating charge, and cancel the one you can't defend. That single move is the one these 50 retirees wish they'd made sooner.